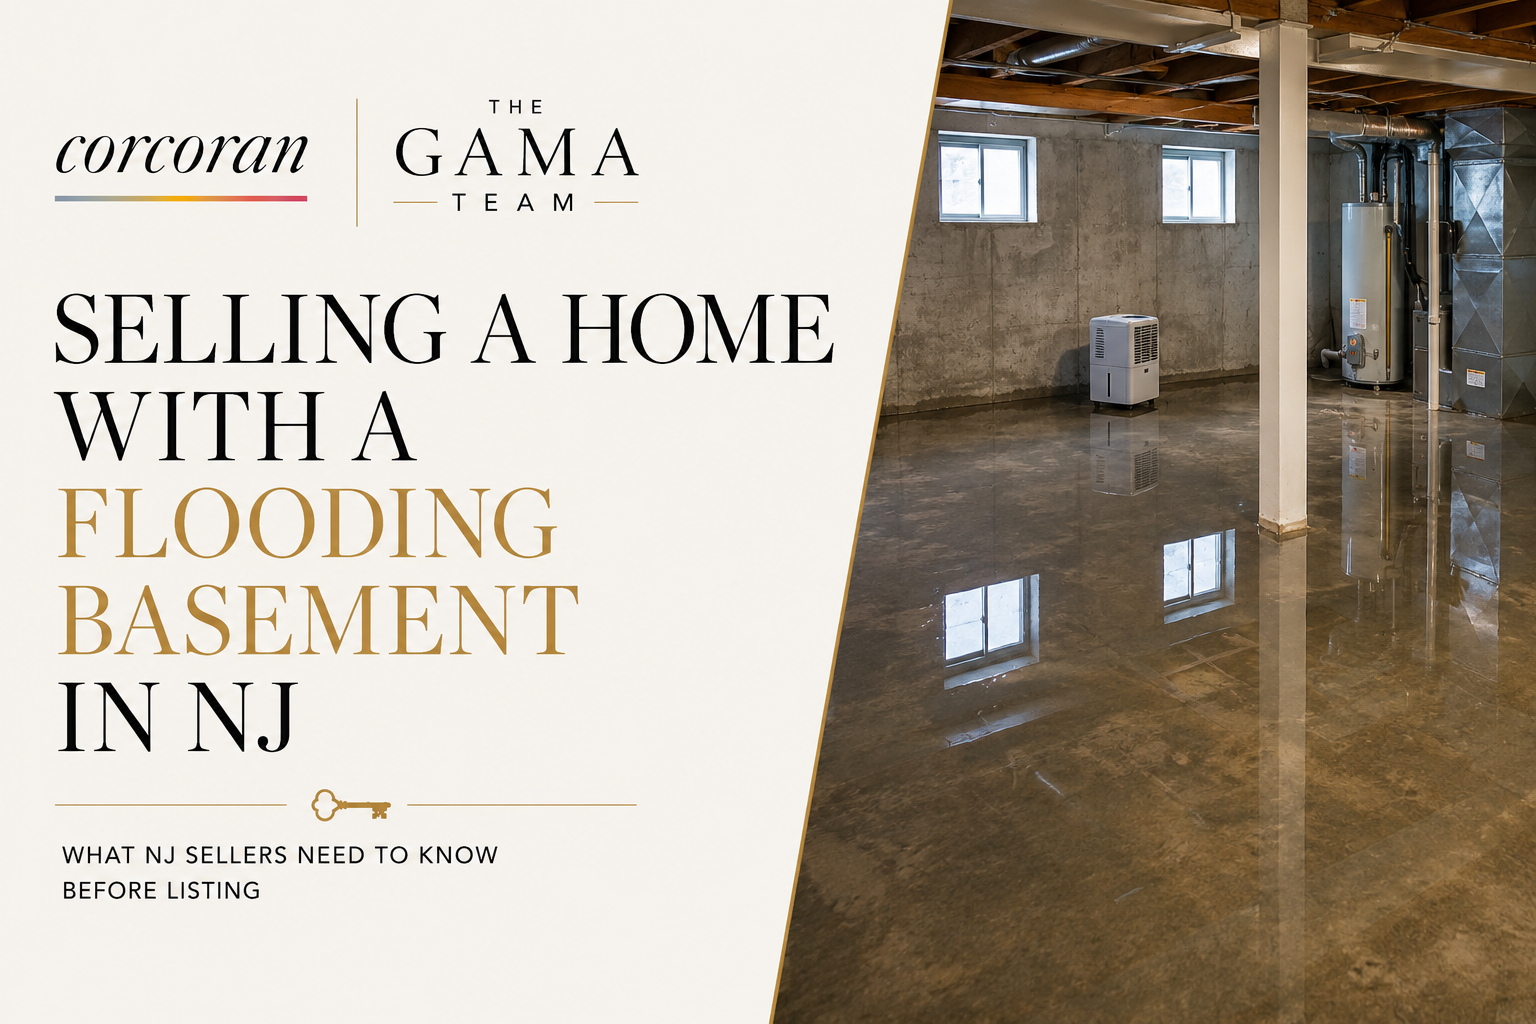
Is it possible to sell a home with a chronically flooding basement in New Jersey? What the law actually requires you to disclose, real remediation options, and how sale price gets adjusted in Westfield, Cranford, Scotch Plains, Mountainside, Maplewood, Montclair, Basking Ridge, and New Providence.
Selling a Home With a Flooding Basement in New Jersey: Is It Possible, and How Do You Actually Do It — The Complete Guide for Westfield, Cranford, Scotch Plains, Mountainside, Maplewood, Montclair, Basking Ridge, and New Providence
Can you sell a home with a basement that floods on a regular basis? Yes — New Jersey law doesn't prohibit it, but it does require you to disclose it in writing, and a successful sale depends on getting three things right: an honest, documented disclosure, a remediation plan matched to the actual severity of the problem, and a price that reflects what the home genuinely is, not what you wish it were.
"Yes, you can sell a home with a flooding basement — we've done it. What changes is the process: full disclosure, a realistic price, and being upfront with buyers about exactly what they're taking on and what it would take to fix it," says Marina Fridman-Rybner of The GAMA Team. That's the honest starting point for this entire guide, and it's worth sitting with for a moment, because a lot of homeowners in this exact situation assume the opposite — that a chronically flooding basement makes a home essentially unsellable, or that the only realistic path is a lowball cash offer from an investor who'll gut the place. Neither is true. It's a harder sale than a dry basement, and it requires a different approach than a typical listing, but it is absolutely a sellable home, and this guide is meant to walk through exactly what that process actually looks like.
We're going to cover what New Jersey law actually requires you to tell a buyer (a genuinely important, relatively new legal development most homeowners don't know about), the real remediation options and what each one actually costs, what happens when a property has flooded enough times to land on a federal watch list most people have never heard of, whether a buyer can even get a mortgage on a property like this, and — the question underneath everything else — how a home's sale price actually gets adjusted to account for a real, documented flooding history.
We're also going to walk through the parts of this situation that don't fit neatly into a single category: what happens during attorney review once a flooding history is on the table, how a finished basement changes the stakes, whether renting instead of selling is actually a viable way to sidestep the decision, and what a buyer evaluating a property like this should be asking that a lot of buyers don't think to ask. If you're facing this situation right now, our goal is that you finish this guide with an actual plan, not just a better understanding of how complicated the situation is.
Wet Basement vs. Flooding Basement: A Distinction Worth Making Precisely
Before going further, it's worth separating two things that get lumped together constantly but sit at very different points on a severity spectrum. A damp basement — some musty smell after a heavy storm, a little moisture on the walls, an occasional puddle near a window well — is a common, usually inexpensive problem to address, and one we've covered in detail in our dedicated guides to basement waterproofing and backyard drainage. A basement that floods on a regular basis — measurable standing water, recurring enough that the homeowner has a name for "flood season," damage to finished space or stored belongings, insurance claims filed more than once — is a fundamentally different situation, both in terms of what it takes to actually fix and in terms of what it means for a sale. This guide is specifically about the second category. If what you're dealing with sounds more like the first, our basement waterproofing and drainage guides are the more directly useful starting point.
Chronic, recurring basement flooding generally traces back to one or more of a small number of underlying causes: a genuinely high water table that regularly rises into the foundation zone; a sump pump system that's inadequate, poorly maintained, or without battery backup (meaning it fails at exactly the moment — a power outage during a major storm — when it's needed most); a foundation with cracks or failed waterproofing that lets groundwater or hydrostatic pressure through; proximity to a river, stream, or other water body with a documented flood history, relevant to a real share of properties in towns like Cranford along the Rahway River corridor; or a combination of these compounding each other during major storm events. Understanding which of these (or which combination) is actually driving your specific situation is the foundation everything else in this guide builds on, the same way it was for the ordinary drainage issues covered in our other guides — except here, given the stakes, a professional assessment isn't optional, it's the necessary first step.
It's also worth distinguishing chronic, recurring flooding from a genuinely one-time event — a burst pipe, a failed water heater, a single unusually severe storm that overwhelmed an otherwise adequate system. A single, isolated incident, properly repaired and unlikely to recur, carries a meaningfully different disclosure and pricing conversation than the recurring, ongoing pattern this guide focuses on, since New Jersey's disclosure law and the broader material-fact doctrine both turn substantially on what a seller actually knows about a property's ongoing condition and history, not on whether any water damage has ever occurred under any circumstances. If your situation is genuinely a single, resolved incident rather than a recurring pattern, it's still disclosable under the flood damage question on the state form, but the remediation and pricing conversation looks considerably more like a standard home sale than the more involved playbook this guide walks through for a true, chronic flooding history.
Checking Your Property's Actual Flood Zone Status
Before any disclosure or pricing conversation can happen accurately, it's worth confirming your property's actual, current FEMA flood zone designation directly, rather than relying on assumption, a neighbor's account, or what you remember from your own purchase closing. New Jersey's Department of Environmental Protection maintains a public flood risk lookup tool that allows a search by street address to determine a property's current Special Flood Hazard Area or Moderate Risk Flood Hazard Area status. Flood maps get revised periodically as FEMA updates its floodplain modeling, which means a property's designation can genuinely change over time — a home that wasn't in a mapped high-risk zone at the time of an original purchase can be remapped into one later, and vice versa, independent of anything that's physically changed about the property itself. Confirming your current, accurate status directly through this tool, rather than an outdated closing document, is a five-minute step worth taking before any of the disclosure or pricing decisions covered throughout the rest of this guide.
What New Jersey Law Actually Requires You to Disclose
This is the single most important, and most recently changed, piece of information in this entire guide, and it's worth understanding in detail because it directly answers the "is this even legal to sell" question at the heart of what brought you to this guide.
New Jersey has enacted a specific flood risk disclosure law, codified at N.J.S.A. 56:8-19.2, that requires sellers of residential and commercial real property to disclose flood-related information directly on an updated version of the state's standard Seller's Property Condition Disclosure Statement. Under this law, every seller in New Jersey must disclose three specific things: whether the property sits within a FEMA-designated Special Flood Hazard Area (commonly referred to as the 100-year floodplain) or a Moderate Risk Flood Hazard Area (the 500-year floodplain); whether the property has experienced flood damage or pooled water resulting from heavy rainfall or another natural flood event; and whether the property is subject to any federal requirement to obtain and maintain flood insurance. This isn't a vague, general "disclose known defects" standard open to interpretation — it's a specific, dedicated section on the mandatory state disclosure form, with specific questions a seller has to answer directly.
"New Jersey now requires you to disclose flood history in writing, so there's no version of this where hiding it is actually an option anymore. We'd rather get ahead of it with documentation than have it come out during attorney review," Marina notes, and the practical implication is direct: if your basement floods on a regular basis, you are legally required to say so, on the record, before a buyer signs a contract. This sits alongside — and reinforces — the broader common-law principle we've discussed in other guides, rooted in New Jersey courts' longstanding rejection of a pure "buyer beware" standard for material facts a seller actually knows. A flood history isn't a gray area you can reasonably choose not to mention; it's now a specific, named question on a mandatory state form.
This is worth framing as genuinely useful information for a seller in this situation, not just a legal obligation to grudgingly comply with. A documented, thorough disclosure — paired with the remediation and pricing strategy covered later in this guide — is what allows a sale to proceed on solid footing, with a buyer who's making an informed decision and can't later claim they weren't told. The alternative — an incomplete or evasive disclosure, followed by a buyer discovering the truth during their own inspection or from a neighbor — doesn't just risk the immediate deal falling through, it risks exactly the kind of post-closing legal exposure the material-fact disclosure doctrine exists to create consequences for.
It's worth being direct about what that exposure actually looks like in practice, since "legal exposure" can otherwise sound abstract. A buyer who discovers, after closing, that a seller knew about and failed to disclose a chronic flooding history generally has real legal recourse — a claim for damages covering the cost of the very remediation the seller should have disclosed, and potentially broader claims depending on the specific facts, since a New Jersey court evaluating this kind of claim is going to look directly at what the seller actually knew, when they knew it, and what they said (or didn't say) about it on the mandatory disclosure form. This isn't a theoretical risk designed to scare sellers into compliance — it's a direct, foreseeable consequence of the exact fact pattern this guide is describing, and it's a meaningfully worse financial and legal position than the honest, disclosed, appropriately priced sale this guide otherwise walks through.
How This Plays Out During Attorney Review
As we've covered in detail in our dedicated guide to New Jersey's mandatory attorney review process, the days immediately following a signed contract are when either side's attorney can renegotiate terms or, in some cases, walk away entirely — and a disclosed flooding history is exactly the kind of fact that frequently becomes a specific point of discussion during this window, even when it was disclosed clearly and accurately from the outset.
A buyer's attorney, upon seeing a flood disclosure, will commonly want to see the specific documentation behind it: prior insurance claims, any existing remediation work and its documentation, and the professional estimate for whatever remediation remains outstanding. This is a normal, expected part of the process for a property with this kind of disclosed history, not a sign the deal is in trouble — but it underscores why having that documentation organized and ready before you even list, rather than scrambling to assemble it once a buyer's attorney requests it, makes for a meaningfully smoother attorney review period. A seller who can produce clear, organized answers to these questions immediately tends to keep a disclosed-flooding transaction moving forward; a seller who needs weeks to track down old claims paperwork or get a contractor out for an estimate risks losing momentum, and sometimes the buyer's confidence, during exactly the window when either side has the easiest path to walking away.
A practical suggestion worth acting on before you ever list: assemble a single, organized file — insurance claims history, any prior remediation invoices and warranties, current professional estimates, and your own completed disclosure form — before your first showing, not after an offer comes in. This isn't just about attorney review specifically; it's genuinely useful throughout the entire process, from setting your own asking price with real numbers behind it to answering a prospective buyer's questions confidently during a showing, well before any formal attorney review period even begins.
Understanding the Federal Flood Claims System: Repetitive Loss and Severe Repetitive Loss
If your home's flooding has actually resulted in insurance claims — not just inconvenience, but paid-out National Flood Insurance Program claims — it's worth understanding a federal classification system that can materially affect your situation, one most homeowners have never heard of until it directly affects them.
A property is classified as a Repetitive Loss (RL) property if it has at least two paid NFIP flood claims exceeding $1,000 each within any ten-year period. A property is classified as a Severe Repetitive Loss (SRL) property under a stricter standard: four or more separate flood claims each exceeding $5,000, or two or more claims whose combined payout exceeds the property's current value. These designations aren't something a homeowner applies for or can decline — they're applied automatically by FEMA's system based on claims history, and homeowners frequently discover their property's status only when it surfaces during an insurance renewal, a claim, or a real estate transaction.
The designation carries real, escalating financial consequences. Severe Repetitive Loss properties face accelerated premium increases specifically because of their claims history — a documented surcharge at renewal, and under the NFIP's current Risk Rating methodology, an annual increase cap of up to 25% (compared to 18% for a typical primary residence without this designation), with the practical result that a large majority of SRL properties reach full, risk-based premium rates within roughly a decade. SRL policies also get moved to a specialized federal servicing facility with stricter oversight than a standard NFIP policy. For a buyer evaluating a property with this designation, that means inheriting not just a flood-prone home, but a specific, already-escalating insurance cost trajectory that a standard flood zone designation alone doesn't carry.
This designation is squarely the kind of fact that falls within New Jersey's disclosure requirements described above — if you know your property carries an RL or SRL designation, or has the claims history that would trigger one, that's precisely the "flood damage" disclosure the state's mandatory form is asking about, and it's worth confirming your property's actual status directly (through your insurance agent or the claims history on file) rather than guessing, since an inaccurate disclosure carries its own risk independent of the underlying flooding itself.
It's worth understanding, too, that this designation is genuinely difficult to escape once triggered, short of the kind of comprehensive remediation or elevation covered later in this guide, or the structured buyout path described further on. Filing fewer claims going forward doesn't retroactively remove a designation already triggered by past claims history — the classification looks backward at the claims record that already exists, not forward at whatever improvements a homeowner makes afterward, unless those improvements are substantial enough to formally requalify the property through FEMA's own review process. This is one more reason the decision of whether and how to file an insurance claim after a flood event is worth thinking through carefully in the moment, ideally with guidance from a knowledgeable insurance professional, since a claim that pushes a property from Repetitive Loss into Severe Repetitive Loss territory carries consequences that persist for years afterward, well beyond the immediate cost the claim was filed to cover.
Remediation Options, Matched to Actual Severity
"Not every wet basement needs the same fix. Sometimes it's a sump pump and a battery backup, sometimes it's full exterior excavation, and once in a while it's bigger than that. Get an actual assessment before you assume which one you're dealing with," says Galina Kaplan of The GAMA Team — and this framing, matching the fix to the actual severity rather than defaulting to either the cheapest or the most extreme option, is the right way to think through what's actually available.
Interior Water Management
An interior system — a perimeter drain installed beneath the basement floor along the foundation, tied to a sump pump that ejects collected water outside — manages water after it's already found its way in, rather than stopping it from entering in the first place. This is the least expensive category of fix, typically running in a range of a few thousand to around ten thousand dollars depending on the basement's size and the specific system installed, and it's a genuinely appropriate solution for minor to moderate seepage. For a basement with a real, chronic flooding history, though, it has a real limitation worth being direct about: water still reaches and passes through the foundation wall itself before the system manages it, and the entire approach depends on a sump pump continuing to function correctly, including — critically — during the power outages that often accompany the exact major storm events that cause the worst flooding. A battery backup system for the sump pump isn't optional in this context; it's the specific piece of equipment that determines whether an interior system actually protects the home during the storm that matters most, or fails at exactly the wrong moment.
Exterior Waterproofing
A more involved, and more expensive, approach: full excavation down to the foundation footing, application of a waterproof membrane directly to the foundation wall, installation of an exterior French drain system, and regrading to direct surface water away from the foundation entirely. This category of fix typically runs several times the cost of an interior-only system — commonly landing somewhere in a range of roughly seven to eighteen thousand dollars for a standard residential foundation, scaling with the size of the home and site accessibility. The advantage is fundamental rather than incremental: exterior waterproofing addresses the root causes (soil saturation, grading, water reaching the foundation at all) rather than managing water after it's already inside, and it's the approach professional guidance consistently points to as the right one for a basement with a genuinely severe or recurring flooding history that an interior system alone hasn't resolved. The trade-offs are real: meaningfully higher cost, a longer and more disruptive installation involving significant yard excavation, and — on some properties — real physical constraints from neighboring structures, utility lines, or a lot too tight to excavate around comfortably. On the positive side of that trade-off, a properly installed exterior system carries a considerably longer expected service life than an interior-only system — commonly cited in a range of two to five decades versus roughly a decade and a half to three decades for interior drainage — which is worth factoring into a cost comparison that looks only at upfront price, since a longer-lived fix that's replaced less often can be the more cost-effective choice over the full time a family expects to own the home, even at a higher initial cost.
Hybrid Systems
For a genuinely severe situation, a combined approach — exterior waterproofing paired with an interior backup system and sump pump — provides redundancy that neither approach offers alone, at a correspondingly higher cost, typically in the range of eight to twenty thousand dollars for a standard residential project. This is often the right answer for a property with a documented, repeated flooding history where the cost of getting it wrong (a failed remediation followed by another flood) is high enough to justify paying for genuine redundancy rather than betting everything on a single system. For a seller specifically, a hybrid system also tends to produce the strongest documentation story during a sale — being able to show a buyer's attorney and appraiser both an exterior fix addressing the root cause and an interior backup managing anything that gets through regardless, rather than relying on the strength of a single system's track record alone.
House Elevation
For a property where the flooding risk is driven fundamentally by the home's elevation relative to a floodplain or a chronically high water table — rather than by a fixable foundation or drainage defect — elevating the structure itself, physically raising it above the flood-prone elevation on a new or extended foundation, is the most drastic and most expensive remediation option, but the only one that fundamentally changes a property's flood risk rather than managing water around an unchanged structure. Costs for this kind of project vary enormously based on the home's size, foundation type, and how high it needs to be raised, but a realistic range runs from roughly twenty-five thousand dollars at the low end to a hundred thousand dollars or more for a larger home or a more significant elevation height, with national average project costs commonly cited around the fifty-thousand-dollar mark. This is a genuinely major undertaking, generally considered only for a property with a severe, well-documented flooding history where lesser remediation options have already been tried and failed, or where a property's specific elevation relative to base flood elevation makes it clear that no amount of drainage or waterproofing work will resolve the underlying exposure.
Sump Pump Maintenance and the Battery Backup Question
Because so much of this guide's remediation discussion returns to the sump pump as a critical component, it's worth a specific word on what proper maintenance and backup actually look like, since a poorly maintained system is a common, avoidable reason an otherwise reasonable interior remediation fails at exactly the wrong moment. A sump pump should be tested directly — pouring water into the sump pit and confirming the pump activates and clears it — on a regular basis, not just assumed to be working because it hasn't obviously failed recently. The pump itself has a finite service life, commonly cited in a range of roughly seven to ten years depending on usage and quality, after which replacement, not repeated repair, becomes the more reliable choice. A battery backup system — which takes over automatically if the primary pump loses power, precisely the scenario that occurs during the exact major storms most likely to cause serious flooding — should have its own battery tested and replaced on its own maintenance schedule, since a backup system with a dead battery provides no actual protection despite giving a false sense of security. For a seller preparing to sell a home with this kind of system in place, documentation of recent testing and battery replacement is exactly the kind of concrete detail that strengthens a disclosure and remediation package during attorney review, described earlier in this guide.
Finished vs. Unfinished Basement Space
It's worth addressing directly how a basement's finish level interacts with everything covered in this guide, since it meaningfully affects both the practical stakes of a flooding history and how a buyer is likely to value the space. A finished basement — with drywall, flooring, and often significant square footage counted informally (though rarely formally, under most appraisal standards) toward a home's livable space — represents considerably more at risk from chronic flooding than an unfinished, utility-only basement, both in terms of the actual damage a flood event causes and in terms of what a buyer is losing access to if the space remains compromised. A seller with a finished basement and a genuine flooding history faces a real decision worth making deliberately: restore the finished space as part of remediation (a meaningfully larger project than remediation alone), or disclose the space as currently unusable and price accordingly, effectively marketing the home based on its unfinished-basement value rather than the finished square footage a buyer might otherwise expect to factor into their own valuation.
When Remediation Isn't the Right Answer: New Jersey's Blue Acres Program
For a property with the most severe flooding histories — specifically, homes that meet FEMA's Repetitive Loss, Severe Repetitive Loss, or substantially-damaged criteria described above — there's a New Jersey-specific alternative worth knowing about that exists entirely outside the standard remediate-and-sell playbook this guide otherwise focuses on.
"If a home has flooded repeatedly and it's on FEMA's repetitive loss list, selling it as-is might not be the only option worth looking at. Sometimes a buyout program is the better financial outcome than fighting the market," Galina Kaplan notes. New Jersey's Blue Acres program, administered by the state's Department of Environmental Protection, acquires flood-prone properties meeting these repetitive-loss criteria directly from homeowners, generally at pre-flood market value, with the acquired land then permanently preserved as open space or natural flood storage rather than being resold for continued residential use. The program exists specifically to break the cycle of repeated flood damage, repeated insurance claims, and repeated rebuilding that characterizes the most severely affected properties, and it's funded substantially through FEMA grant dollars specifically allocated for this purpose.
This isn't a fit for every flooding basement covered by this guide — it's specifically aimed at the most severe, most repetitively damaged properties, and it's a genuinely different transaction than a standard real estate sale, involving a state agency rather than a private buyer, its own eligibility review process, and its own timeline. But for a homeowner facing a property that's flooded repeatedly enough to carry an RL or SRL designation, and who's genuinely weighing whether continued remediation and an eventual private sale makes more financial sense than an alternative, structured exit, it's worth a direct conversation with Blue Acres or a knowledgeable local attorney before committing fully to the private-market path this guide otherwise describes — the comparison between the two paths is worth making deliberately, with real numbers, rather than defaulting to a private sale simply because it's the more familiar process.
Can a Buyer Even Get a Mortgage on a Home Like This?
This is a practical question worth addressing directly, because it shapes your entire realistic buyer pool. If your property sits within a FEMA-designated Special Flood Hazard Area, any federally regulated mortgage lender is legally required to mandate flood insurance as a condition of the loan — this isn't a lender preference, it's a requirement tied to the National Flood Insurance Act, and it applies regardless of whether the specific basement flooding you're dealing with is related to river or coastal flooding or a separate, unrelated groundwater or drainage issue. A buyer purchasing your home with a conventional, federally backed mortgage will need to have flood insurance in place at closing, and will need to keep it in place for the life of the loan — a real, ongoing cost that becomes part of their overall decision about whether and how much to offer.
For a property carrying a Repetitive Loss or Severe Repetitive Loss designation specifically, this gets more complicated still: the insurance cost trajectory described earlier in this guide (accelerating toward full risk-based rates) means a buyer's ongoing carrying cost isn't just higher than a typical home's, it's specifically higher and still climbing, which a well-informed buyer's lender — and increasingly, a well-informed buyer themselves — will factor directly into their own underwriting and affordability calculations. Some lenders apply additional scrutiny or overlays to properties with a documented severe flooding history beyond the baseline federal flood insurance requirement, which can meaningfully narrow the pool of buyers able to secure financing at all, independent of the home's list price.
This is precisely why the buyer pool for a home with genuine, chronic flooding history skews so heavily toward cash buyers and investors, a dynamic covered in more detail below — not because traditional buyers are uninterested as a category, but because the financing path for a traditional, mortgage-dependent buyer is genuinely more constrained on a property like this than on a comparable home without the same history.
One detail worth knowing specifically: if remediation is completed before a buyer's loan closes, and that remediation is properly documented, a traditional lender's underwriting concerns generally ease considerably, since the property they're actually financing at closing reflects the fixed, current condition rather than the flooding history itself. This is one more reason a completed, well-documented remediation tends to open up a meaningfully wider buyer pool — including buyers who'd otherwise have been effectively priced out by financing constraints alone — than a sale where remediation remains an open, unresolved item for the buyer to sort out after closing.
How Sale Price Actually Gets Adjusted
This is the question underneath everything else in this guide, and it's worth grounding in real research rather than a guess, because the honest picture is more nuanced than a single discount percentage.
Academic research out of Stanford, examining nationwide housing data, found that when a property is newly designated within a floodplain, single-family home values decline by roughly 2% on average — a modest discount in the context of everything else that drives home value. But the same research found a striking gap between that observed discount and what a fully rational market, accounting for the actual cost of comprehensively insuring against flood damage, should produce: the researchers calculated that prices should reasonably fall somewhere between 4.7% and 10.6% to fully reflect that risk, meaning the broader market for ordinary flood-zone properties appears to significantly underprice the actual financial risk involved. The same research found that more sophisticated, institutional buyers — home rental companies and similar large-scale investors — discount flood-zone properties roughly five additional percentage points below what typical individual homebuyers do, a meaningful signal that more risk-literate buyers price this exposure more conservatively than the broader market.
It's important to be precise about what that research actually measured: general flood-zone designation, not a property with an actual, documented, repeated flooding history. A home that's simply located within a mapped floodplain but has never flooded is a fundamentally different pricing situation than a home with real, disclosed flood damage and possibly an RL or SRL designation attached to it — and we're not aware of an equivalently rigorous, published study quantifying the specific discount for that more severe category, so we'd rather tell you that honestly than manufacture a specific percentage to make this section sound more authoritative than the evidence actually supports.
What we can say, based on what we see in actual transactions: "You don't price a flooding basement by guessing. You get real remediation quotes, you understand what a cash buyer would actually pay versus a traditional buyer, and you price toward the buyer pool you're realistically going to attract," as Galina Kaplan puts it. In practice, that means building your price from the ground up using a few concrete inputs: a comparable sale analysis using homes without a similar flooding history as your starting benchmark, a documented, professional remediation estimate for the specific fix your property actually needs, and a realistic assessment of whether you're pricing toward a traditional, mortgage-financed buyer pool (which, as covered above, may be genuinely narrower for your specific property) or toward the cash and investor buyer pool discussed in the next section, since those two buyer pools price risk differently and expect a meaningfully different discount from an equivalent dry-basement comp.
A Worked Example: Building an Actual Price
Numbers make this concrete in a way general guidance doesn't, so it's worth walking through a simplified, illustrative example of how the pricing approach described above actually comes together in practice.
Say a home in our market would be worth roughly $900,000 based on recent comparable sales of similar, dry-basement homes nearby. The seller has a documented flooding history — two prior insurance claims, not severe enough to trigger a Severe Repetitive Loss designation but enough to require disclosure — and obtains a professional exterior waterproofing estimate of $14,000 to fully address the underlying cause. Rather than guessing at a discount, the seller uses that estimate as a concrete starting point: the comparable-sale value, minus the documented remediation cost, minus some additional amount reflecting the narrower buyer pool and the inherent uncertainty a disclosed history introduces even with a clear remediation plan attached, might reasonably land the listing price somewhere in the neighborhood of $860,000 to $875,000, depending on how motivated the seller is to sell quickly versus hold out for a buyer willing to pay closer to the top of that range.
Compare that to a seller in the same situation who simply guesses at a round-number discount without the underlying documentation — arbitrarily knocking $50,000 off the comparable-sale value, for instance, with no specific remediation estimate to point to. That seller is likely to either leave real money on the table (if the actual remediation cost turns out to be considerably less than their guessed discount) or face a buyer's attorney pushing back hard during attorney review once they see an unsupported number next to a specific, documented issue. Building the price from real inputs — a comparable baseline, a professional remediation quote, and a realistic assessment of buyer-pool constraints — produces a number that holds up under the kind of scrutiny a disclosed flooding history is guaranteed to invite, which an arbitrary guess simply doesn't.
Common Misconceptions Worth Correcting
A handful of assumptions come up often enough in our conversations with sellers in this situation that they're worth addressing directly.
The belief that a home with a genuine flooding history simply can't be sold through a traditional MLS listing is generally incorrect — as this guide has covered throughout, a fully remediated, well-documented property can absolutely sell to a traditional, mortgage-financed buyer, though the disclosure and, often, the completed remediation documentation need to be in order first.
The belief that hiring a cash-buying company or investor is always the only realistic option is also incorrect for many properties in this situation, and often leaves real money on the table for a seller who could have achieved a stronger outcome through remediation and a traditional listing, given the time and resources to pursue that path.
The belief that a flood zone designation and an actual flooding history are the same thing, carrying the same disclosure and pricing implications, is a common but importantly incorrect conflation — as covered in detail above, a property can sit within a mapped flood zone and have never actually flooded, which is a meaningfully different disclosure and pricing situation than a property with real, documented flood damage, even though both require disclosure under New Jersey's law.
And the belief that a single remediation project permanently and completely eliminates all future flood risk is worth tempering as well — even a properly executed exterior waterproofing system reduces risk substantially rather than eliminating it entirely, particularly for a property in a genuine floodplain, which is part of why ongoing flood insurance remains a relevant consideration even after a successful remediation project, not just a formality to satisfy during the sale itself.
Timing Considerations for a Flooding-History Sale
As we've covered in detail in our broader guide to timing a home sale, seasonality shapes buyer behavior across our entire market — and it has a specific, additional dimension worth understanding for a property with a disclosed flooding history. Listing shortly after a major regional storm event, when flooding is fresh in every prospective buyer's mind across the broader market, tends to be a particularly difficult window for a property with its own disclosed flooding history, since buyer anxiety about flood risk generally runs highest precisely when it's been in the local news. Conversely, completing remediation work during a drier stretch of the calendar and listing once the work is finished and documented, rather than rushing a listing to catch a specific seasonal window, tends to serve a seller in this situation better than optimizing purely for the general seasonal patterns that apply to a typical, dry-basement home.
The Buyer Pool You're Actually Selling To
Understanding who's actually likely to buy a home with a documented, chronic flooding history shapes both your pricing strategy and your marketing approach, and it's worth being realistic about this rather than assuming a standard buyer pool applies.
Cash investors represent a significant share of the realistic buyer pool for a property in this situation. They typically purchase as-is, without requiring the seller to complete repairs first, and can close quickly without the financing contingencies and lender-driven flood insurance requirements covered above — but they price in the risk and the remediation cost themselves, which generally means an offer meaningfully below what a comparable dry-basement home would command, reflecting both the actual remediation cost and their own required margin.
Traditional, MLS-listed buyers remain a real possibility, particularly for a property where remediation has already been completed (or is being completed as part of the sale) and the flooding history, while disclosed, is clearly resolved rather than ongoing. This buyer pool is more sensitive to financing constraints (as covered above) and more likely to require a completed, professional remediation before closing rather than taking on the project themselves, but it's also the buyer pool most likely to pay closer to full market value for a property where the underlying issue has genuinely been fixed.
For-sale-by-owner is a path some homeowners consider specifically to avoid the disclosure and marketing challenges of a traditional listing, but in our experience it tends to produce a narrower buyer pool than either of the other two paths, without the speed advantage of a dedicated cash-investor sale or the price advantage of a fully remediated MLS listing — generally the least advantageous of the three realistic paths for this specific situation.
"A disclosed problem with a clear fix and a number attached is something a buyer can work with. An undisclosed problem they discover later is something they'll never trust you on again, and it can unwind the whole deal," Marina emphasizes, and this is really the thread connecting all three paths: whichever buyer pool you're ultimately selling to, a clear, documented, well-quantified disclosure is what makes the transaction workable, and an unclear or incomplete one is what tends to derail it, regardless of which type of buyer you're dealing with.
Should You Carry More Than the Minimum Required Insurance?
For a homeowner in this situation who isn't selling immediately, or who's completing remediation before listing, it's worth a brief word on flood insurance coverage levels beyond whatever minimum a lender might require. Standard NFIP policies carry specific coverage caps that, particularly for a higher-value home in our market, may not fully cover a total loss — worth understanding directly with your insurance agent rather than assuming a standard policy limit matches your actual rebuild cost. Private flood insurance, available as an alternative or supplement to NFIP coverage, sometimes offers higher coverage limits or different terms worth comparing directly, particularly for a property with a claims history where NFIP premiums are already elevated. This isn't primarily a real estate question — it's an insurance question best directed to a qualified agent — but it's worth raising proactively rather than discovering a coverage gap only after a future flood event, especially for a homeowner planning to remediate and hold the property for some period before eventually selling.
It's also worth understanding that flood insurance and homeowners insurance are genuinely separate policies covering genuinely separate risks — a standard homeowners policy typically excludes flood damage entirely, which is precisely why a dedicated flood policy exists as its own product rather than an add-on endorsement. A homeowner who's confirmed they have adequate homeowners coverage but hasn't separately confirmed their flood coverage is, in practice, uninsured against the exact risk this entire guide is about, regardless of how comprehensive their broader homeowners policy might be.
Marketing to Two Different Buyer Types at Once
Given the buyer-pool dynamics covered throughout this guide — a narrower, financing-constrained traditional buyer pool alongside a cash-and-investor pool with different expectations entirely — a listing strategy for a home with a disclosed flooding history often benefits from deliberately speaking to both audiences simultaneously, rather than picking one and marketing exclusively to it from the outset.
In practice, this means listing materials and remarks that lead with transparency rather than attempting to minimize or bury the disclosed issue (which, given the mandatory disclosure requirements covered above, would be discovered regardless), paired with concrete, specific information — the professional remediation estimate, any completed work and its documentation, the property's actual flood zone and claims history — that lets both a cash buyer and a well-qualified traditional buyer evaluate the property on real terms rather than guesswork. A listing that reads as evasive or vague about a known issue tends to scare off the more sophisticated, better-informed segment of both buyer pools, while a listing that's specific and matter-of-fact about exactly what's being disclosed and what it would take to address tends to attract buyers who've already made their peace with the situation and are evaluating the property on its real merits and real price, which is generally the more productive negotiation to be having.
What to Do If You're the One Buying
Flipping this guide's perspective for a moment: if you're evaluating a home with a disclosed flooding history rather than selling one, the same information covered throughout this guide is worth actively requesting rather than passively accepting whatever's on the disclosure form. Ask directly for the property's specific NFIP claims history and whether it carries an RL or SRL designation, since this affects your own future insurance costs meaningfully, not just the immediate purchase price. Request the seller's own remediation estimates, or obtain your own from a professional you trust, rather than relying solely on a number the seller's motivated to present favorably. Confirm directly with your own lender exactly how the property's flood zone status and disclosed history affects your specific financing terms and required insurance, ideally before you're deep into a specific negotiation on this particular property. And factor the full picture — purchase price, remediation cost, and ongoing insurance trajectory — into your actual offer, rather than negotiating purchase price in isolation and being surprised by the other costs later.
A Realistic Decision Framework: Fix, Disclose-and-Discount, or Explore a Buyout
Pulling everything in this guide together into a practical framework: if your basement's flooding is moderate and traceable to a specific, fixable cause (an inadequate sump system, a grading issue, a foundation crack), and you have the resources and timeline to complete a proper remediation before listing, doing so and then selling at or near full market value to a traditional buyer is generally the strongest financial outcome available, for the same reasons covered in our broader guide to fixing known issues before listing rather than leaving them for a buyer to discover.
If your flooding is more severe, or you don't have the resources or timeline to complete remediation first, disclosing fully, obtaining a professional remediation estimate to share with prospective buyers, and pricing realistically toward either a cash-investor or fully-informed traditional buyer is the more common, and still entirely workable, path — the one this guide has focused on in the most detail, because it's the situation most homeowners in this position actually face.
And if your property carries a genuine Repetitive Loss or Severe Repetitive Loss designation, or a flooding history severe enough that you suspect it might, it's worth having the Blue Acres conversation described above before committing to either of the first two paths, since for the most severely affected properties, a structured buyout may produce a better financial outcome than continuing to fight an increasingly expensive insurance and remediation cycle in pursuit of a private sale.
Renting Instead of Selling: Worth Considering, or Not?
Some homeowners in this situation, particularly if remediation isn't immediately affordable and a private sale feels premature, consider renting the property out rather than selling it. It's worth addressing directly why this generally isn't the path we'd recommend for a home with a genuine, chronic flooding history, beyond the general landlord considerations we've covered in other guides.
Renting out a home with an undisclosed or unremediated flooding history to a tenant raises its own, separate set of legal exposure questions around habitability and landlord disclosure obligations to tenants, independent of the real estate-specific disclosure law covered throughout this guide. A tenant experiencing repeated basement flooding has their own set of legal remedies against a landlord who knew about the condition, which means renting doesn't actually avoid the disclosure and liability questions this guide has focused on — it simply shifts them into landlord-tenant law rather than resolving them. And practically, a rental property still needs to be insured, still carries the same escalating premium trajectory described above if it carries an RL or SRL designation, and still requires the same eventual remediation-or-sale decision this guide walks through, simply deferred rather than avoided. For most homeowners in this specific situation, renting tends to be a delay rather than a genuine solution, worth pursuing only with a clear-eyed plan for how and when the underlying flooding issue actually gets addressed, not as a way to sidestep the decision indefinitely.
Choosing an Agent Who's Actually Handled This Before
Not every real estate agent has direct experience marketing and pricing a home with a genuine, disclosed flooding history, and it's worth asking directly about this specific experience when you're choosing who to work with, rather than assuming general listing experience translates automatically to this more specialized situation.
A few things worth asking directly: has this agent handled a disclosed flood-history sale before, and what was the outcome? How do they think about pricing toward the dual buyer-pool dynamic described throughout this guide, rather than defaulting to a single, standard pricing approach? Are they comfortable working alongside the specific professionals this situation often requires — a waterproofing contractor for remediation estimates, an attorney well-versed in the flood disclosure law, potentially a Blue Acres contact for the most severe cases — rather than treating the listing as a standard transaction with an unusual disclosure attached? An agent who can speak specifically and confidently to these questions, rather than treating your situation as a standard listing with one extra disclosure item, is more likely to help you navigate toward the strongest realistic outcome for your specific property.
This also extends to how an agent handles marketing photography and showings, which deserves a direct mention. A listing that tries to photograph around or minimize a finished basement's visible condition, only for a buyer to discover the reality during an in-person showing, undermines the trust this entire guide has emphasized building through clear, upfront disclosure. An agent experienced with this specific situation will generally recommend photographing and describing the space honestly, letting the documented remediation plan and adjusted price do the work of making the listing attractive to the right buyer, rather than trying to visually undersell an issue that's going to be disclosed in writing regardless.
What a Home Inspector and Appraiser Will Both Flag
If you're proceeding with a private sale, it's worth understanding what happens on both sides of that transaction once a disclosed flooding history is on the table. A buyer's home inspector will typically look closely at foundation walls for cracks, staining, and efflorescence; check the sump pump system's condition, age, and whether it includes a battery backup; assess grading and downspout placement as covered in our drainage guide; and, especially for a disclosed flooding history, may recommend a more specialized structural or waterproofing-specific inspection beyond a standard general home inspection.
An appraiser, separately, is tasked with establishing the property's value for lending purposes, and a documented flooding history — particularly one with an RL or SRL designation attached — is exactly the kind of factor that can lead an appraiser to apply a specific downward adjustment relative to comparable sales without a similar history, compounding the financing constraints covered earlier in this guide. This is worth anticipating directly rather than being surprised by: a seller who's already obtained their own professional remediation estimate and, ideally, completed at least some of the recommended work, gives both the inspector and the appraiser less room for the kind of open-ended uncertainty that tends to produce the most conservative, most discounted assessment.
A Word on Mold and Health Considerations
We'd be doing this topic a disservice if we didn't acknowledge, briefly, that chronic basement flooding frequently raises mold concerns, since persistent moisture is exactly the condition mold needs to establish itself. We want to be direct about the boundary of what we can speak to here: we're real estate agents, not industrial hygienists, mold remediation specialists, or medical professionals, and if visible mold or a persistent musty odor is part of your specific situation, a qualified mold inspection and remediation assessment — separate from the waterproofing remediation this guide focuses on — is a genuinely necessary step, not an optional add-on. Mold remediation costs and requirements vary enormously based on the extent of growth and the materials affected, and it's a specialized enough area that we'd always recommend a dedicated professional assessment rather than treating it as something a general contractor or waterproofing company addresses as a matter of course. If mold is part of your property's history, it's also worth understanding that it may be its own separate disclosure consideration beyond the flood-specific disclosure requirements covered throughout this guide — a question worth raising directly with your attorney alongside everything else covered here.
What This Guide Doesn't Cover
In the interest of being genuinely useful rather than falsely comprehensive, it's worth naming directly what falls outside this guide's scope. We haven't covered mold remediation in any technical depth, for the reasons just described. We haven't covered the structural engineering assessment a severely compromised foundation might require, which is its own specialized field beyond general waterproofing contracting. We haven't covered the specific mechanics of filing or contesting an NFIP claim, which your insurance agent or a public adjuster is better positioned to walk you through than a real estate guide. And we haven't covered the detailed application process for New Jersey's Blue Acres program, which the program's own staff can explain far more specifically than we can from the real estate side of that conversation.
What we've focused on instead is the real estate-specific piece of this puzzle: what you're legally required to tell a buyer, how the major remediation categories compare in cost and appropriateness, how financing and insurance realities shape your actual buyer pool, and how a defensible sale price actually gets built. For everything else, the professionals named throughout this guide — a waterproofing or structural engineer, a mold remediation specialist, an insurance agent, and a real estate attorney familiar with New Jersey's flood disclosure law — are the right resources, often working together as a team the same way they would on any other complex transaction.
Common Mistakes We See
Assuming disclosure is optional or a matter of personal judgment. As covered in detail above, New Jersey's flood disclosure law makes this a specific, mandatory question on the standard state form, not a gray area a seller gets to interpret generously.
Defaulting to the most expensive remediation without an actual severity assessment. Just as an interior-only system can be genuinely inadequate for a severe, recurring flooding history, a full exterior excavation or elevation project can be genuine overkill for a problem that a properly specified interior system with battery backup would have resolved just as effectively at a fraction of the cost.
Pricing based on comparable sales without a flooding history, without adjustment. A standard comparable sales analysis, built entirely from dry-basement comps, systematically overstates what a property with a genuine, disclosed flooding history will actually command, for the buyer-pool and financing reasons covered throughout this guide.
Not checking whether the property carries an RL or SRL designation before pricing or marketing it. This federal classification carries real, escalating cost implications for a buyer's future insurance premiums, and marketing or pricing a property without knowing its actual status risks a mismatch between your asking price and what an informed buyer's own underwriting will support.
Overlooking the Blue Acres conversation for the most severely affected properties. As covered above, this alternative path is worth exploring specifically before committing fully to a private sale, for homeowners whose properties meet the program's repetitive-loss criteria.
Skipping the insurance conversation until late in the process. Whether it's confirming your own property's actual designation, understanding a buyer's financing-related insurance requirements, or considering coverage beyond the required minimum, insurance touches nearly every section of this guide — treating it as a formality to handle right before closing, rather than a factor shaping your strategy from the outset, tends to produce avoidable surprises late in a transaction.
Assuming a contractor's verbal assessment is sufficient documentation. For a disclosure and pricing strategy that needs to hold up during attorney review and appraisal, a written, detailed professional estimate carries far more weight than an informal verbal opinion, even from a genuinely qualified contractor — get it in writing from the start, not after a buyer's attorney asks for it.
Town-by-Town: A Few Local Notes
Cranford, given its position along the Rahway River corridor covered in detail in our dedicated guide to the town's flood zones, is the market in our coverage area where chronic, river-related basement flooding comes up most often, and where the FEMA Special Flood Hazard Area designation discussed throughout this guide is most likely to be directly, rather than hypothetically, relevant to a specific listing.
Westfield, Scotch Plains, Mountainside, Maplewood, Montclair, Basking Ridge, and New Providence see chronic basement flooding less frequently tied to a mapped floodplain and more often rooted in the groundwater, foundation, and drainage causes covered earlier in this guide — a meaningful distinction, since a home in one of these towns without a formal flood zone designation may still face genuine, disclosure-worthy chronic flooding without carrying the same federally mandated insurance requirements a Special Flood Hazard Area designation would trigger.
Across all eight towns, the specific FEMA flood zone designation for any given property is a matter of public record, available through New Jersey's own flood risk lookup tools, and worth confirming directly for your specific address rather than assuming based on general neighborhood reputation, since flood zone boundaries can run through a single block in ways that aren't always intuitive from the street.
This last point deserves real emphasis: we regularly see homeowners assume their property's flood status based on their town's general reputation, or on where a well-known local flood event happened to cause visible damage, rather than on their specific parcel's actual, mapped designation. A home two blocks from a documented flood-prone street can carry a completely different designation than the properties directly on it, and the reverse is just as true — a home that feels far from any obvious water body can still fall within a mapped floodplain due to drainage patterns that aren't visible from the surface. This is exactly why the flood risk lookup tool described earlier in this guide is worth using directly for your specific address, in every one of our towns, rather than relying on neighborhood-level assumptions in either direction.
Worked Scenarios From Our Market
A Cranford Seller Who Disclosed and Priced Realistically
A Cranford homeowner along the Rahway River corridor, with a basement that's flooded several times over the years and generated more than one insurance claim, works with an attorney to confirm the property's actual NFIP claims history and disclosure obligations before listing. Rather than attempting remediation they can't fully afford, they obtain a professional exterior waterproofing estimate, include it directly in their disclosure materials, and price the home specifically toward the cash-and-investor buyer pool described in this guide. The home sells within a reasonable timeframe to a buyer who factors the disclosed estimate directly into their own renovation plans.
A Westfield Homeowner Who Fixed It First
A Westfield homeowner with a basement flooding problem traced to an undersized sump pump without battery backup invests in a proper hybrid interior-and-exterior system before listing, at a cost considerably below what a full remediation for a more severe problem would have required. With the fix completed and documented, the disclosure becomes a straightforward, resolved-issue conversation rather than an ongoing concern, and the home sells to a traditional, mortgage-financed buyer at a price much closer to comparable dry-basement homes than an unremediated listing would have achieved.
A Basking Ridge Family Exploring a Buyout
A Basking Ridge family whose property has flooded repeatedly enough to carry a Severe Repetitive Loss designation initially assumes their only option is a steeply discounted private sale. Their attorney recommends a direct conversation with New Jersey's Blue Acres program given the property's specific designation, and the family ultimately determines that a structured buyout, at a value reflecting the home's pre-flood condition, produces a better financial outcome than continuing to absorb an escalating insurance premium trajectory while marketing the home privately.
A Montclair Buyer Who Asked the Right Questions
A buyer evaluating a Montclair home with a disclosed flooding history requests the seller's specific NFIP claims documentation and a professional remediation estimate before finalizing an offer, confirms with their own lender exactly how the disclosed history affects their financing and required insurance, and negotiates a purchase price reflecting the actual, quoted remediation cost rather than a vague, unquantified discount — a clean, well-informed transaction that worked specifically because both sides had real numbers rather than assumptions to negotiate around.
A Maplewood Seller Who Chose the Cash-Buyer Path
A Maplewood seller facing a genuinely severe, longstanding basement flooding problem, without the funds or timeline to complete remediation before a planned relocation, discloses fully and markets specifically toward cash investors rather than attempting a traditional MLS listing. The resulting offer reflects a real discount relative to a dry-basement comparable, but the transaction closes quickly, without financing contingencies or an extended negotiation over repairs the seller wasn't in a position to complete anyway — the right trade-off for their specific circumstances, even though it wasn't the highest theoretically achievable price.
A Scotch Plains Seller Who Restored Finished Space
A Scotch Plains homeowner with a finished basement damaged by chronic flooding weighs whether to restore the finished space as part of remediation or disclose it as currently unusable. After getting quotes for both the underlying waterproofing fix and the cosmetic restoration, they determine the combined cost is still less than the value gap between a home marketed with usable finished space versus one marketed as unfinished, and proceed with the full restoration before listing — a decision that only made sense once they had real numbers for both paths rather than guessing at which was more cost-effective.
A Mountainside Buyer Who Negotiated on Documented Numbers
A buyer evaluating a Mountainside home with a disclosed, moderate flooding history requests the seller's specific remediation estimate before making an offer, then gets their own second opinion from a different waterproofing contractor to confirm the number is reasonable. Finding the two estimates closely aligned, the buyer proceeds with confidence, structuring their offer around the confirmed remediation cost rather than either accepting the seller's number blindly or assuming, without evidence, that it was understated.
A Glossary of Terms Used in This Guide
Repetitive Loss (RL) — A FEMA/NFIP classification applied to a property with at least two paid flood insurance claims exceeding $1,000 each within any ten-year period.
Severe Repetitive Loss (SRL) — A stricter FEMA/NFIP classification applied to a property with four or more flood claims each exceeding $5,000, or two or more claims whose combined payout exceeds the property's value.
Special Flood Hazard Area (SFHA) — A FEMA-designated high-risk flood zone, commonly called the 100-year floodplain, where federally regulated mortgage lenders are required to mandate flood insurance.
Moderate Risk Flood Hazard Area — A FEMA-designated flood zone with lower but still meaningful risk, commonly called the 500-year floodplain, distinct from the higher-risk Special Flood Hazard Area.
N.J.S.A. 56:8-19.2 — New Jersey's statute requiring sellers of real property to disclose flood zone status, flood damage history, and applicable flood insurance requirements on the state's standard disclosure form.
Blue Acres — A New Jersey Department of Environmental Protection program that acquires flood-prone properties meeting repetitive-loss criteria directly from homeowners, converting the land to permanent open space or flood storage.
Interior waterproofing system — A drainage and sump pump system that manages water after it has entered a basement, generally appropriate for minor to moderate seepage rather than severe, recurring flooding.
Exterior waterproofing — A more comprehensive remediation approach involving excavation, foundation membrane application, and exterior drainage, addressing water intrusion at its source rather than managing it after entry.
House elevation — The most extensive remediation option, physically raising a structure above its flood-prone elevation, generally considered only for the most severe, well-documented flooding situations.
Base flood elevation — The specific elevation, established by FEMA for a given area, to which a structure would need to be raised to be considered above the mapped flood risk.
Battery backup sump system — A secondary power source for a sump pump that activates automatically during a power outage, addressing the specific failure mode most likely to occur during a major storm event.
Comparable sales analysis (comps) — A pricing method based on recent sales of similar nearby properties, which requires deliberate adjustment when applied to a property with a disclosed flooding history that comparable properties lack.
Flood Risk Notification Tool — New Jersey's public online lookup allowing homeowners to confirm a specific property's current FEMA flood zone designation by address.
Private flood insurance — Flood coverage offered by private insurers as an alternative or supplement to standard NFIP policies, sometimes offering different coverage limits or terms worth comparing directly.
Work With a Team That Won't Sugarcoat It or Overstate It
A chronically flooding basement is one of the harder conversations we have with sellers, and we think it deserves a direct, honest answer rather than either false reassurance or unnecessary alarm. It's a real, disclosable, price-affecting issue — and it's also a genuinely solvable one, with real paths to a fair, workable sale, whether that's a full remediation and a traditional listing, a disclosed, realistically priced sale to a cash buyer, or, for the most severely affected properties, a structured buyout through New Jersey's own Blue Acres program.
What we'd want anyone in this situation to take away above everything else in this guide: the worst outcomes we see aren't the ones where a home has a genuine, disclosed flooding history and sells for a fair, well-documented, appropriately discounted price. They're the ones where a seller tried to minimize or hide the issue, got caught during attorney review or after closing, and ended up in a far worse financial and legal position than an honest disclosure would ever have produced. The path this guide describes is more work upfront — getting real remediation estimates, understanding your property's actual flood zone and claims history, pricing deliberately rather than guessing — but it's the path that actually protects you, both as a matter of New Jersey law and as a matter of getting the strongest realistic outcome available for your specific property.
If you're facing this situation in Westfield, Cranford, Scotch Plains, Mountainside, Maplewood, Montclair, Basking Ridge, or New Providence, we'd encourage you to reach out before you've settled on a path, so we can walk through your specific property's history, your realistic options, and what each one would actually mean for your bottom line. Reach out to The GAMA Team at Corcoran Sawyer Smith, 52a Elm Street, Westfield, NJ, or call or text 908-379-0525, or connect through thegamateam.com.
Marina Fridman-Rybner & Galina Kaplan The GAMA Team | Corcoran New Jersey Real Estate | Home Sellers | Home Buyers | NYC to NJ Relocation
This article is intended for general informational purposes and reflects our understanding of New Jersey's flood disclosure requirements under N.J.S.A. 56:8-19.2, National Flood Insurance Program repetitive loss criteria, and general remediation industry cost and practice information at the time of writing. It is not legal, insurance, engineering, or contracting advice. Flood zone designations, insurance program rules, and remediation costs vary by property and change over time; confirm current requirements directly with a licensed New Jersey real estate attorney, a qualified waterproofing or structural professional, your flood insurance provider, and, where relevant, the New Jersey Blue Acres program before making decisions based on this guide.
Sources
- Selling a House With Water Damage — HouseCashin
- NJDEP Blue Acres Program
- What Happens if Your Home Is on the Repetitive Loss List — Flood Insurance Guru
- New Jersey Flood Risk Disclosure Requirements — Nixon Peabody
- Can the Bank Force Me to Buy Flood Insurance? — HelpWithMyBank.gov
- Interior vs. Exterior Basement Waterproofing — The Basement Guide
- Cost to Raise a House — Fixr
- Flood Risk's Impact on Home Values — Stanford Report
Check out this article next